Discount Rates in India
The chart shows Numerica’s zero-coupon discount rate curve for India: annually compounded spot rates by maturity, constructed each trading day from Government of India securities traded on the Clearing Corporation of India’s NDS-OM platform. Hover over the curve for the rate at any maturity, and over a point for the bond behind it. Earlier days can be selected from the date picker.
Numerica’s constructed curve is published daily from 28 September 2026. Curves for dates before then are the Zero Coupon Yield Curve published by CCIL, which this page displayed until that date. CCIL’s published curve, and the zero curve published by Financial Benchmarks India (FBIL), are used as independent checks on each day’s constructed curve.
Methodology
Data Collection: Outright trades in Government of India dated securities and treasury bills on CCIL’s NDS-OM platform, taken at 5:30 PM IST on each trading day, together with the Reserve Bank of India’s policy repo rate.
Data Filtering: Fixed-coupon dated Government of India securities and treasury bills are used. Bills maturing within about 36 days, floating-rate bonds, state development loans and special securities are excluded, and a traded yield that sits off the day’s term structure is down-weighted before fitting.
Historical Aggregation: When fewer than 3 bonds trade on a given day, we aggregate trades from up to 7 prior days (unique securities only) to ensure adequate data points for curve fitting.
Curve Fitting: Nelson-Siegel parametric model with volume-weighted fitting. Securities are weighted by the square root of their relative trading volume, cash flows follow the G-Sec convention of semi-annual coupons on a 30/360 basis, treasury bills set the short end, and the RBI policy repo rate is a light guard rail at the overnight tenor.
Temporal Smoothing: Alpha (confidence score) ranges from 0.0 to 1.0 based on: bond count (20%), volume (50%), liquidity (15%), fit quality (10%) and maturity coverage (5%). Smoothed curve = α × today’s curve + (1-α) × previous curve. On a day with 20 or more securities traded the day’s fit is used as it is, unsmoothed.
Reference Check: Each day’s curve is compared with the zero-coupon curves published by CCIL and FBIL for the same date, restated to annual compounding. A curve that departs from both published curves beyond tolerance (25 basis points root mean square, or 50 at any maturity), where those two agree with each other, is replaced on this page by CCIL’s published curve until it has been reviewed.
Full technical documentation →
Appropriate Use
Follow judgement:
- IAS 19, Ind AS 19, AS 15 discount rate determination for employee benefit obligations
- IFRS/Ind AS compliance and financial reporting
- Actuarial valuations requiring INR-denominated discount rates
- Benchmarking and economic analysis
Not Appropriate For
Any other purpose not listed above, including:
- Trading, investment decisions, or portfolio management
- Pricing derivatives or structured products
- High-frequency or intraday applications
- Regulatory capital calculations requiring approved vendor data
Disclaimers
Intended users: This data is provided exclusively for Numerica clients and their professional advisors working on Ind AS 19, IAS 19, AS 15 and other IFRS and Indian GAAP compliance matters.
No warranty: No representations or warranties regarding accuracy, completeness, or timeliness. Yield curves are fitted models; thin trading may affect reliability.
Professional judgment required: Users must exercise independent professional judgment and verify data before use in financial reporting. Ultimate responsibility for discount rate selection rests with the reporting entity and their auditors.
No liability: Numerica shall not be liable for losses, damages, or adverse consequences arising from use of this data.
INR Discount Rates at vs 31 March 2026
Published
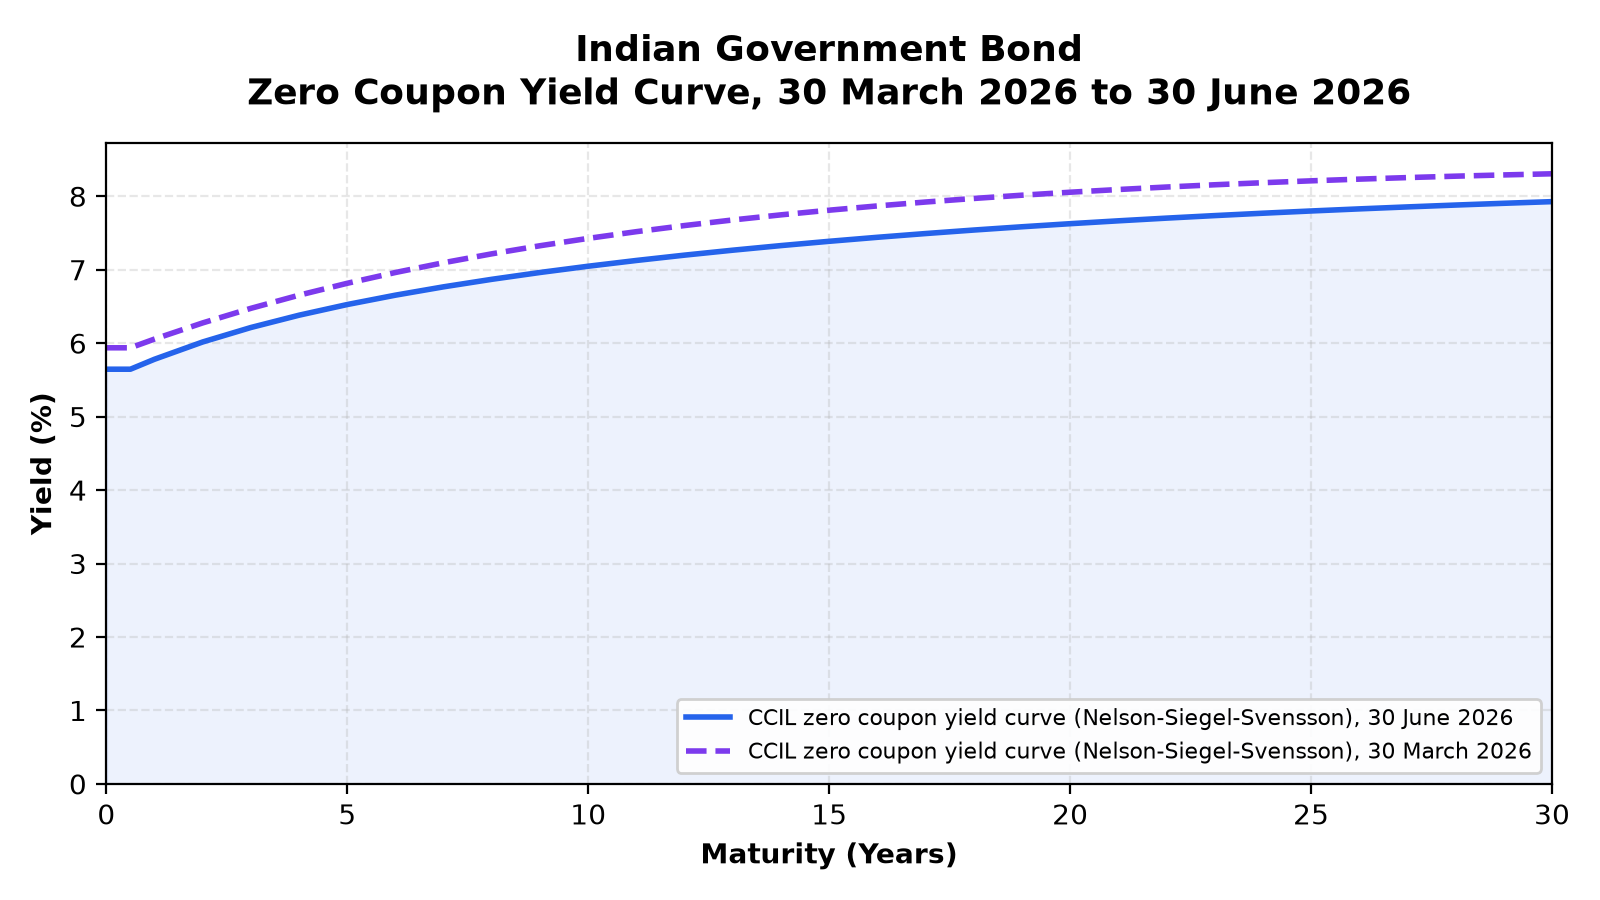
INR discount rates fell at every term between 31 March 2026 and 30 June 2026, by 34 basis points on average. The 10-year rate moved from 7.43% to 7.05%, and lower rates mean indicatively a 3% to 4% increase in gratuity and leave liabilities at a 10-year duration.
Key Takeaways
- 10-year rate: moved from 7.43% to 7.05% on CCIL’s Zero Coupon Yield Curve since 31 March 2026, a change of -38 basis points.
- Short and long ends: -27 basis points at 1 year and -26 at 2 years, against -42 at 15 years and -43 at 20 years. Every term fell.
- Flatter curve: the 10-year less 2-year slope went from 1.15% to 1.03%, a change of -12 basis points.
- Liabilities: lower discount rates mean higher gratuity and leave liabilities, indicatively a 3% to 4% increase at a 10-year duration.
1. What Changed Since 31 March 2026
| Term (Years) | 31 March 2026 | 30 June 2026 | Change (bps) |
|---|---|---|---|
| 1 | 6.06% | 5.78% | -27 |
| 2 | 6.28% | 6.02% | -26 |
| 3 | 6.47% | 6.21% | -26 |
| 5 | 6.82% | 6.53% | -29 |
| 7 | 7.10% | 6.77% | -33 |
| 10 | 7.43% | 7.05% | -38 |
| 15 | 7.81% | 7.39% | -42 |
| 20 | 8.05% | 7.63% | -43 |
| 30 | 8.31% | 7.93% | -38 |
Changes are calculated from unrounded rates. See our disclaimer.
Level. Rates fell at every term between 31 March 2026 and 30 June 2026. The average change across tenors was -34 basis points.
Short end. The 1-year rate moved from 6.06% to 5.78% (-27 basis points) and the 2-year from 6.28% to 6.02% (-26 basis points).
Long end. The 15-year rate moved from 7.81% to 7.39% (-42 basis points), the 20-year from 8.05% to 7.63% (-43 basis points) and the 30-year from 8.31% to 7.93% (-38 basis points). The long end fell further than the short end.
Slope. The 10-year rate moved from 7.43% to 7.05% (-38 basis points), against -26 basis points at 2 years. The 10-year less 2-year slope therefore went from 1.15% at 31 March 2026 to 1.03% at 30 June 2026, a change of -12 basis points: the curve flattened.
2. Impact on Gratuity and Leave Liabilities
Ind AS 19 and AS 15 valuations discount future benefit payments on a government bond curve such as this one. The rate is read at the liability’s duration, typically 8 to 15 years for gratuity and 5 to 10 years for leave encashment.
Lower discount rates increase the present value of these liabilities, so obligations measured at 30 June 2026 are higher than at 31 March 2026, other things being equal. The longer the duration, the larger the effect. The table shows the rate change at typical durations and the indicative effect.
| Duration (Years) | Rate Change (bps) | Indicative Liability Impact |
|---|---|---|
| 5 | -29 | About 1% increase |
| 8 | -35 | 2% to 3% increase |
| 10 | -38 | 3% to 4% increase |
| 12 | -40 | 4% to 5% increase |
| 15 | -42 | 5% to 6% increase |
Indicative only: the figures above are first order and reflect only the rate change at each duration. The actual impact depends on your workforce profile and plan design, and your actuary computes it in the valuation.
Where the change is recognised. Lower discount rates produce an actuarial loss. Under Ind AS 19, remeasurements of post-employment benefits such as gratuity are recognised in other comprehensive income (OCI). Under AS 15, actuarial gains and losses are recognised in profit and loss. Leave encashment is generally an other long-term employee benefit, so its actuarial gains and losses go to profit or loss under both standards.
Need an actuarial valuation? We prepare Ind AS 19 and AS 15 valuations of gratuity and leave encashment; contact us to discuss your next valuation.
For finance teams, auditors and actuaries preparing Ind AS 19 and AS 15 gratuity and leave encashment valuations.
How Numerica constructs its curve, and when CCIL’s curve is shown instead →