Methodology
Data Collection: Taken from Saudi Exchange (Tadawul) government bond and sukuk transactions at 5:00 PM KSA.
Data Filtering: Only confirmed trades are considered for bootstrapping and curve-fitting.
Historical Aggregation: When fewer than 3 bonds trade on a given day, we aggregate trades from up to 7 prior days (unique ISINs only) to ensure adequate data points for curve fitting.
Curve Fitting: Nelson-Siegel parametric model with volume-weighted optimization. Bonds are weighted by relative trading volume; SAMA reverse repo rate provides a short-end anchor.
Temporal Smoothing: Alpha (confidence score) ranges from 0.0 to 1.0 based on: bond count (20%), volume (50%), maturity coverage (15%), fit quality (10%), and same-day trading proportion (5%). Smoothed curve = α × today’s curve + (1-α) × previous curve.
Full technical documentation →
Appropriate Use
Follow judgement:
- IAS 19 discount rate determination for employee benefit obligations
- IFRS compliance and financial reporting
- Actuarial valuations requiring SAR-denominated discount rates
- Benchmarking and economic analysis
Not Appropriate For
Any other purpose not listed above, including:
- Trading, investment decisions, or portfolio management
- Pricing derivatives or structured products
- High-frequency or intraday applications
- Regulatory capital calculations requiring approved vendor data
Disclaimers
Intended users: This data is provided exclusively for Numerica clients and their professional advisors working on IFRS/IAS 19 compliance matters.
No warranty: No representations or warranties regarding accuracy, completeness, or timeliness. Yield curves are fitted models; thin trading may affect reliability.
Professional judgment required: Users must exercise independent professional judgment and verify data before use in financial reporting. Ultimate responsibility for discount rate selection rests with the reporting entity and their auditors.
No liability: Numerica Consulting shall not be liable for losses, damages, or adverse consequences arising from use of this data.
Saudi Arabia Discount Rates at vs 31 December 2025
Published
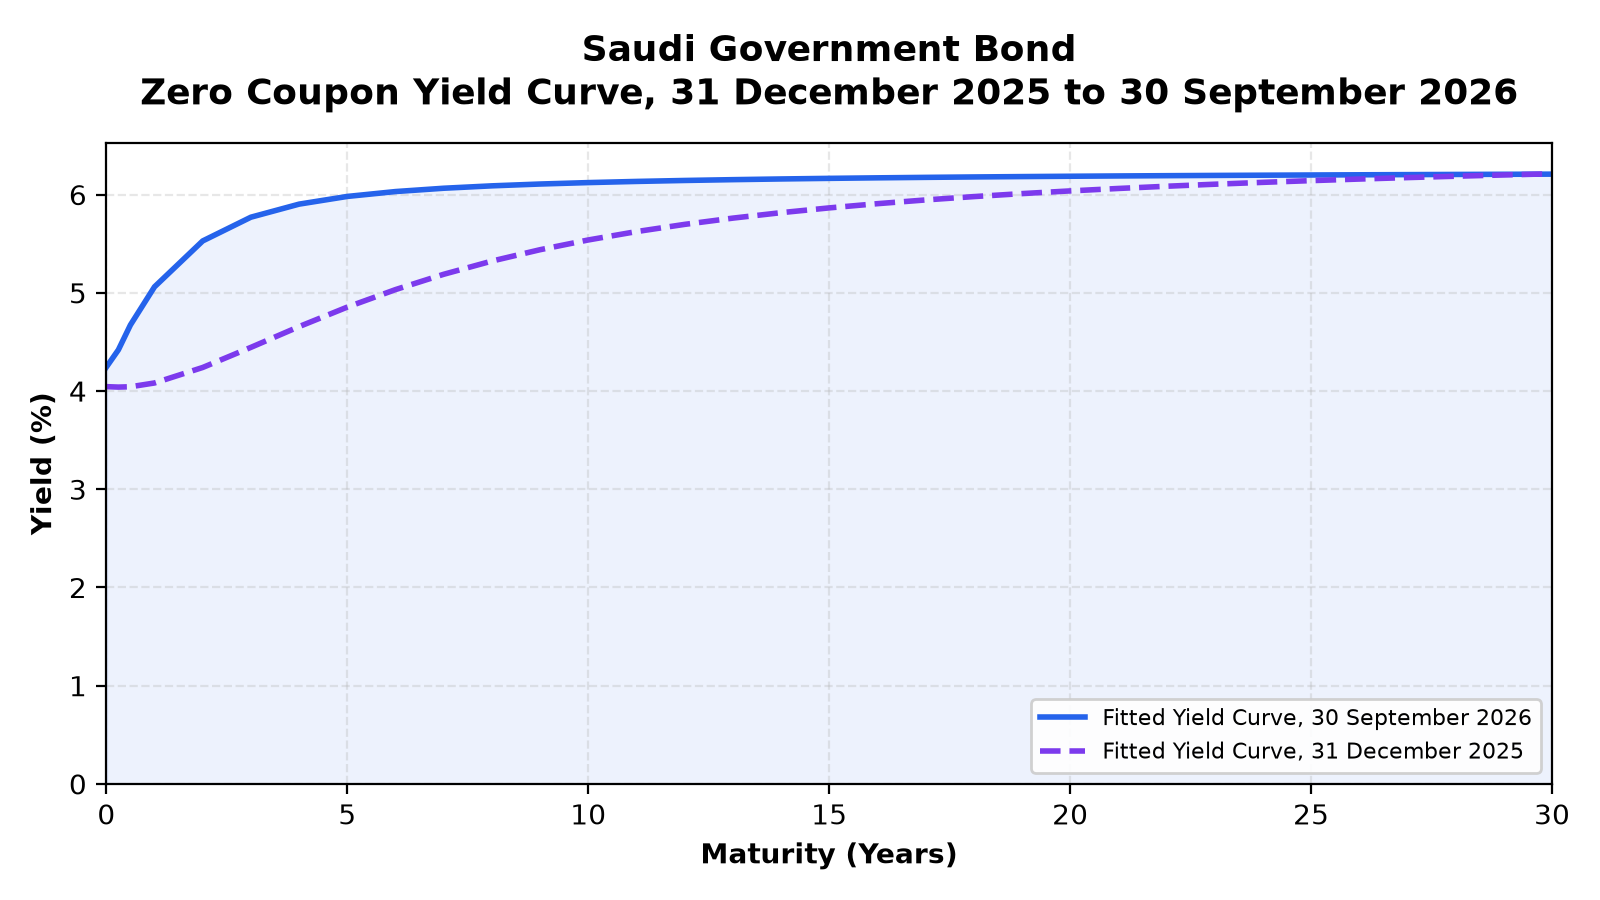
Saudi Arabia discount rates rose at every term up to 20 years between 31 December 2025 and 30 September 2026, with the 10-year rate up 58 basis points to 6.12%. The indicative EOSB liability impact is a decrease at every duration: 5% to 6% at 5 to 10 years and 4% to 5% at 12 and 15 years.
Key Takeaways
- 10-year rate: from 5.54% to 6.12%, a rise of 58 basis points.
- Short end up most: the 3-year rate rose 133 basis points to 5.77%.
- Long end steadier: the 30-year rate was 6.21% on both dates.
- Curve flatter: the slope (10-year less 2-year) narrowed from 1.30% to 0.59%.
- Policy rate: the SAMA reverse repo rate was 3.75% at 31 December 2025 and 4.00% at 30 September 2026.
- Liabilities: an indicative 5% to 6% decrease at 5 to 10 years’ duration, 4% to 5% at 12 and 15 years.
1. What Changed Since 31 December 2025
| Term (Years) | 31 December 2025 | 30 September 2026 | Change (bps) |
|---|---|---|---|
| 1 | 4.08% | 5.06% | +98 |
| 2 | 4.24% | 5.53% | +129 |
| 3 | 4.44% | 5.77% | +133 |
| 5 | 4.85% | 5.98% | +113 |
| 7 | 5.19% | 6.06% | +88 |
| 10 | 5.54% | 6.12% | +58 |
| 15 | 5.86% | 6.17% | +30 |
| 20 | 6.04% | 6.19% | +15 |
| 30 | 6.21% | 6.21% | 0 |
Changes are calculated from unrounded rates. See our disclaimer.
Level. Averaged across the terms in the table, rates rose by 74 basis points. The 30 September 2026 curve lies above the 31 December 2025 curve up to 20 years and meets it at 30 years.
Short end. The largest rises were at 2 and 3 years, 129 and 133 basis points, to 5.53% and 5.77%. The 1-year rate rose 98 basis points to 5.06%, the 5-year rate 113 basis points to 5.98% and the 7-year rate 88 basis points to 6.06%.
Long end. The 10-year rate moved from 5.54% to 6.12%, a rise of 58 basis points. Further out the rises were smaller: 30 basis points at 15 years, 15 at 20 years and none at 30 years.
Slope. The 10-year rate less the 2-year rate was 1.30% at 31 December 2025 and 0.59% at 30 September 2026. The curve flattened by 70 basis points.
Policy rate. The SAMA reverse repo rate was 3.75% at 31 December 2025 and 4.00% at 30 September 2026.
Since 30 June 2026. The 10-year rate moved from 5.50% to 6.12%, a rise of 62 basis points. The slope narrowed from 0.79% to 0.59%, a flattening of 20 basis points.
2. Impact on EOSB Liabilities
Where an IAS 19 valuation of SAR End of Service Benefits discounts on this curve, the rate is read at the duration of the liability. EOSB durations are typically 5 to 12 years.
Rates rose at every duration in the table, so the indicative impact is a decrease throughout: higher discount rates reduce the present value of the obligation. The rises were largest at short durations, but longer liabilities are more sensitive to each basis point, so the percentage decreases are close together.
| Duration (Years) | Rate Change (bps) | Indicative Liability Impact |
|---|---|---|
| 5 | +113 | 5% to 6% decrease |
| 8 | +77 | 5% to 6% decrease |
| 10 | +58 | 5% to 6% decrease |
| 12 | +45 | 4% to 5% decrease |
| 15 | +30 | 4% to 5% decrease |
Indicative only: The impacts above are indicative and first order, reflecting only the rate change at each duration. The actual impact on a plan depends on its workforce profile and plan design, and the actuary computes it as part of the valuation.
Where the change is recognised. Under IAS 19, remeasurements of the EOSB obligation arising from changes in the discount rate are recognised in other comprehensive income (OCI), not in profit or loss.
Need an actuarial valuation? We prepare IAS 19 valuations of End of Service Benefits for employers in Saudi Arabia; contact us to discuss your next reporting date.
For finance teams, auditors and actuaries preparing IAS 19 End of Service Benefits valuations. For IFRS 17 discounting of SAR insurance liabilities, the curve can serve as the risk-free starting point, before any illiquidity premium is added.
Full methodology for the discount curve →